Taal
De wereldwijde fotovoltaïsche (PV) zonne-energiesector bevindt zich op een kritiek omslagpunt wat betreft de kosten. Een combinatie van snel stijgende grondstofprijzen, forse prijsstijgingen voor lithiumcarbonaat en de aanstaande afschaffing van de export-btw-korting door China vanaf april, zorgt voor een fundamentele verandering in de prijsdynamiek binnen de gehele toeleveringsketen.
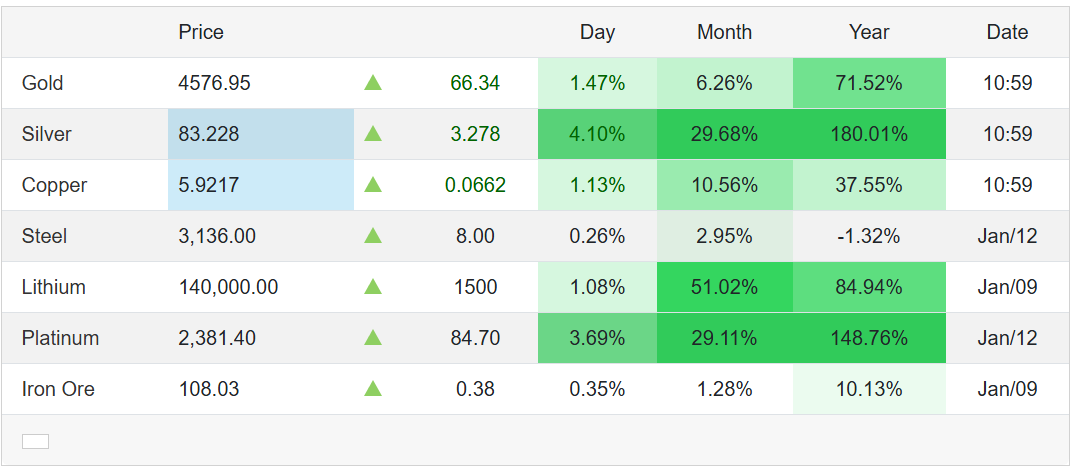
De afgelopen weken zijn de prijzen van diverse grondstoffen die essentieel zijn voor PV-systemen versneld gestegen.
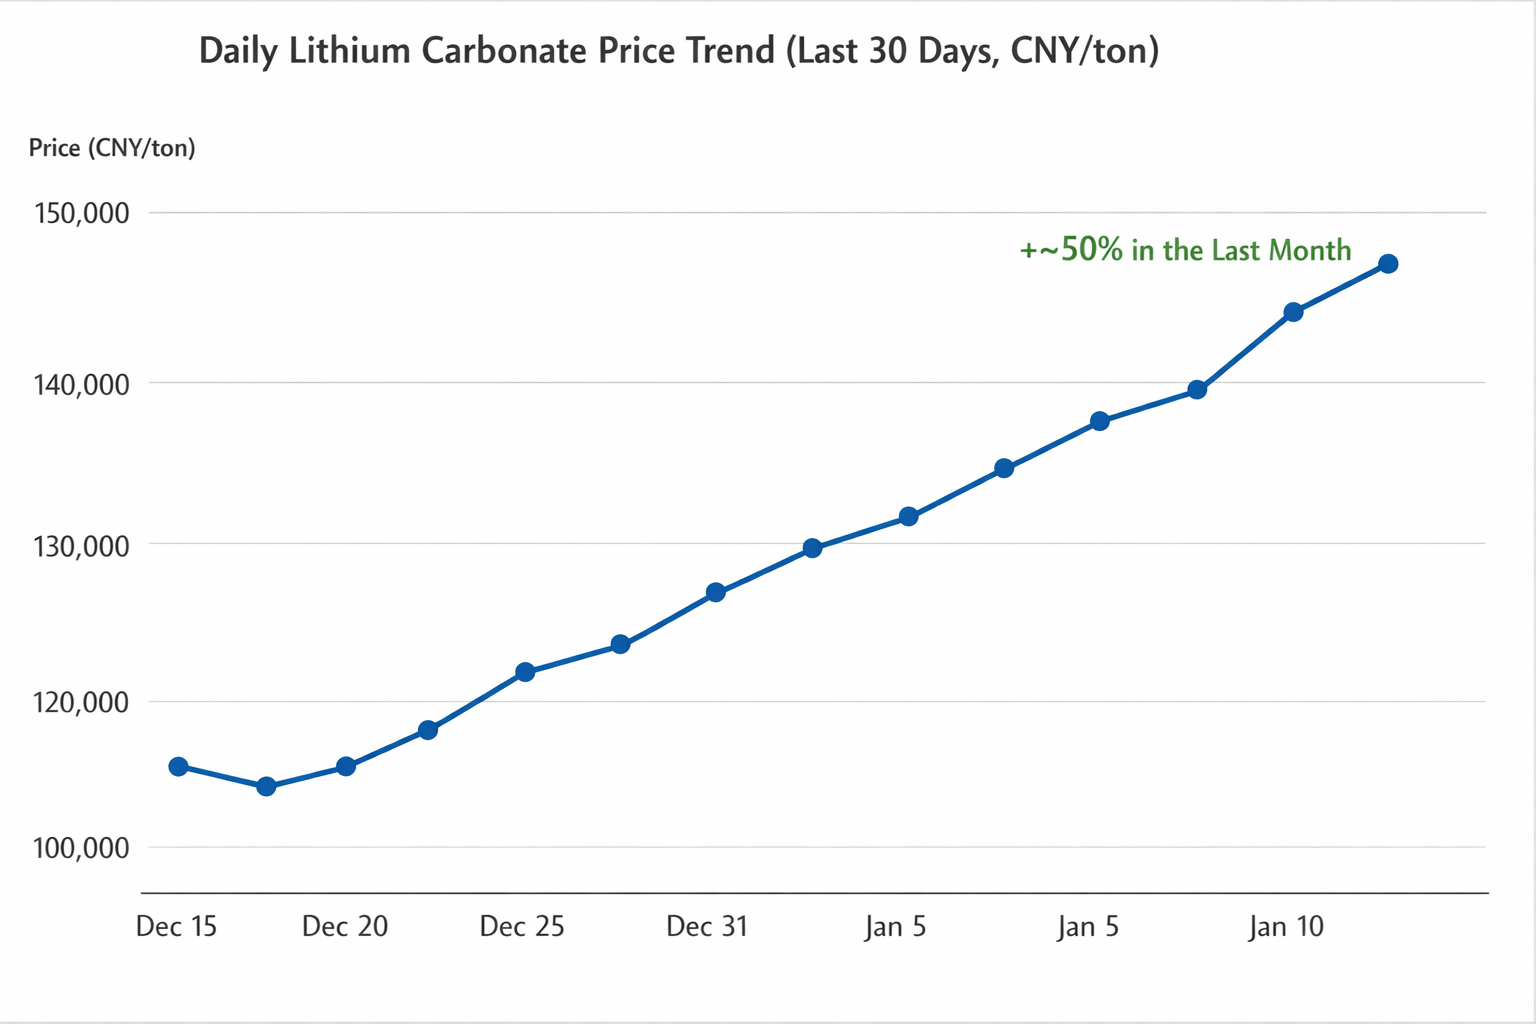
De prijzen van lithiumcarbonaat zijn sterk gestegen als gevolg van lage voorraden, door beleid gestuurde vraagverwachtingen en de aanhoudende groei van de vraag naar batterijen vanuit de energieopslag- en elektrische voertuigensector. Dit leidt direct tot hogere kosten voor PV-plus-opslagsystemen.
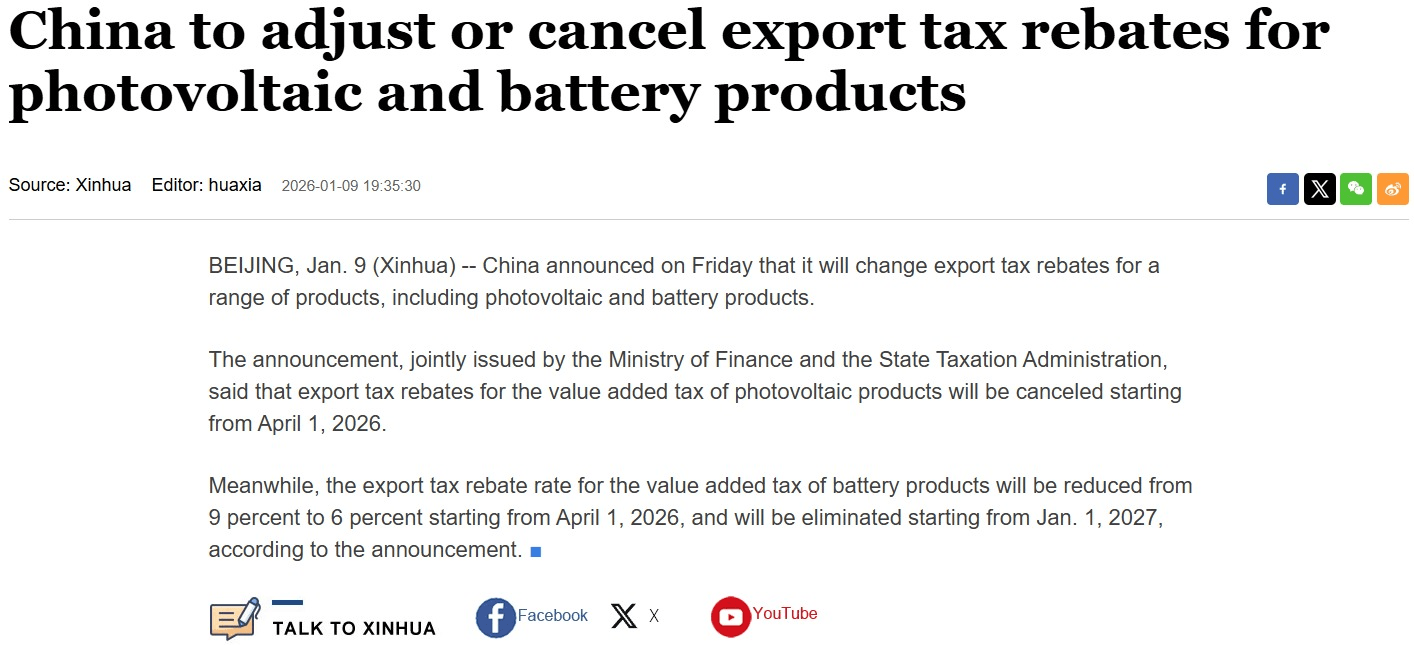
China schaft vanaf april de btw-teruggave op de export van fotovoltaïsche producten af, waarbij de teruggave op lithiumbatterijen geleidelijk wordt afgebouwd.
Dit betekent een structurele kostenstijging voor geëxporteerde PV- en energieopslagproducten, waardoor fabrikanten gedwongen worden de prijzen te verhogen en de leveringen te versnellen in aanloop naar de implementatie.
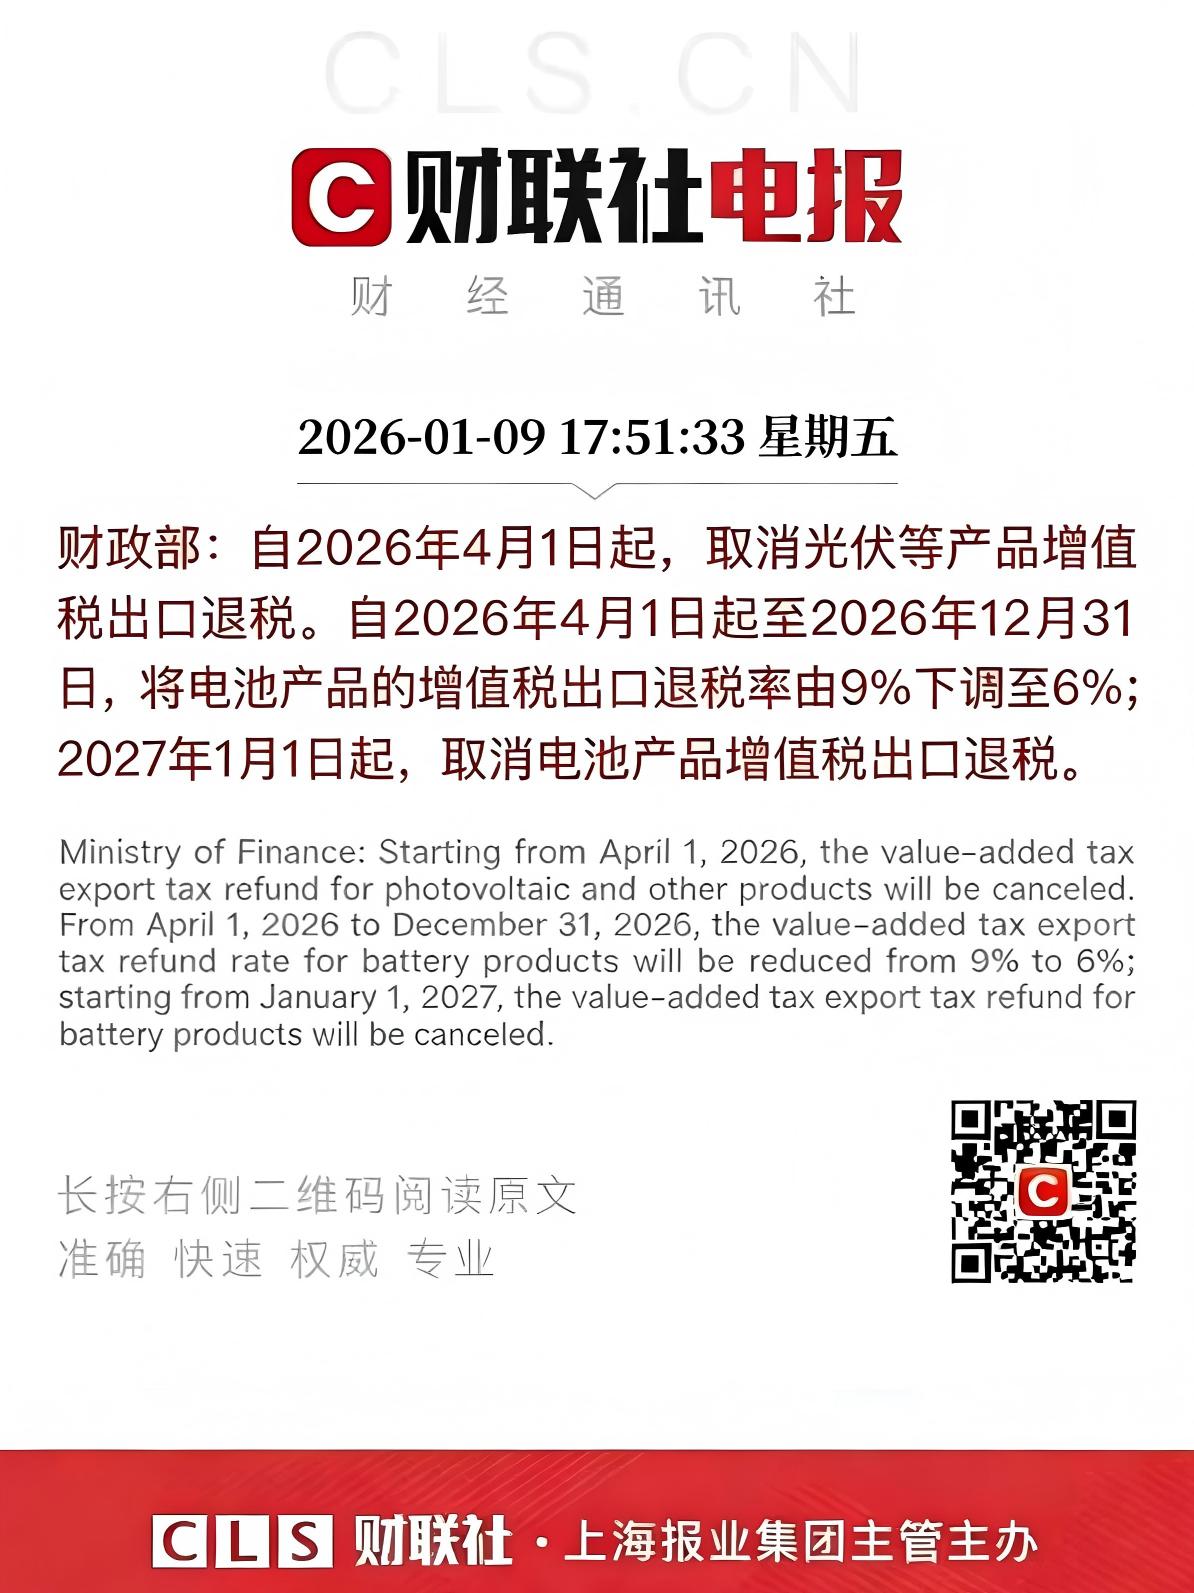
De samenloop van grondstofinflatie en beleidswijzigingen verkleint de inkoopmogelijkheden.
*Uitgestelde aankopen brengen nu een hoger kostenrisico met zich mee.
*Vroegtijdige bestellingen helpen de prijs vast te leggen en de levering te garanderen.
Three things follow from the cost moves above. First, panel prices stop falling and start tracking upstream polysilicon and aluminium. Second, storage gets more expensive before it gets cheaper, because lithium carbonate leads the battery chain. Third, the window to lock a price narrows: the convergence of raw material inflation and the export rebate change means quotes that were valid for thirty days are now valid for ten.
For procurement teams the practical response is to fix the specification early and price the whole bill of materials at once, rather than optimising panels first and discovering the battery cost later. A solar industry buyer who locks cells, cells-to-module conversion and balance of system in one contract avoids the worst of the gap between a panel quote and a delivered system price.
It also changes where the savings are. When module prices rise, the engineering margin moves to configuration: right-sizing the array to the real load, cutting oversized inverter capacity, and specifying storage against the overnight load rather than a rule of thumb. That is work that shows up in the bill of materials, not in the headline price per watt.
Procurement teams tracking these moves can cross-check the policy side against the US DOE Solar Energy Technologies Office, which publishes solar industry cost and deployment data on the same cycle. For the import and duty side of a purchase, see our Philippines solar import guide.
If you are budgeting a build this year, the honest answer is that the solar industry has moved from a deflationary market to a volatile one. Plan for a price band rather than a single number, and ask your supplier which components in the quote are fixed and which track the spot market.
We publish our own solar industry bill-of-materials pricing with a validity window and a named component list, so a buyer can see exactly which line items moved and why when a quote is refreshed. That transparency is the only workable answer to a market where the same system prices differently three weeks apart.
One more practical note for anyone pricing this year: the solar industry gap between a panel quote and a delivered system price is where most budgets break, because freight, duties and balance of system move on different cycles from the modules themselves. Ask for all three in one number.
 English English
 Arabic
 Spanish
 French
 Dutch
 Portuguese