لغة
يشهد قطاع الطاقة الشمسية الكهروضوئية العالمي نقطة تحول حاسمة في التكاليف. فمزيج من الارتفاع السريع في أسعار المواد الخام، والزيادة الحادة في تكاليف كربونات الليثيوم، وإلغاء الصين المرتقب لإعفاءات ضريبة القيمة المضافة على الصادرات ابتداءً من أبريل، يُعيد تشكيل ديناميكيات التسعير بشكل جذري عبر سلسلة التوريد بأكملها.
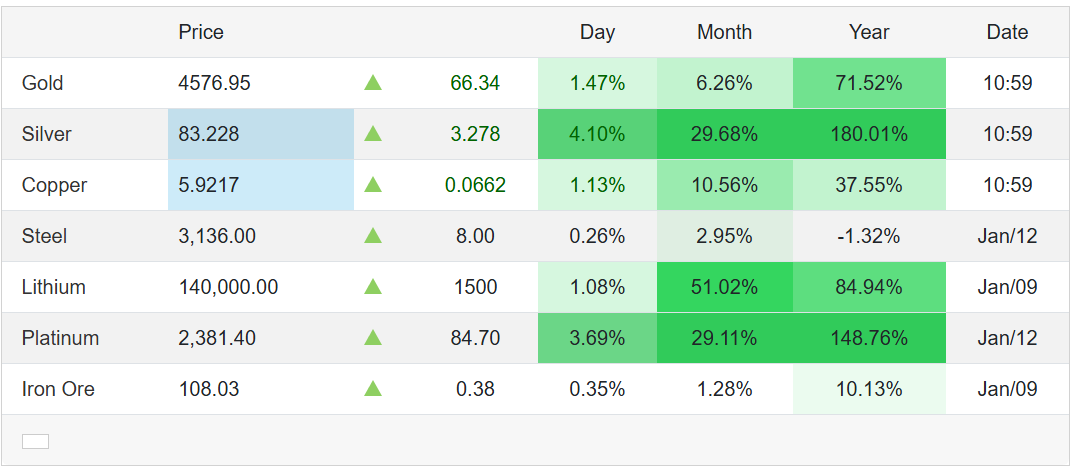
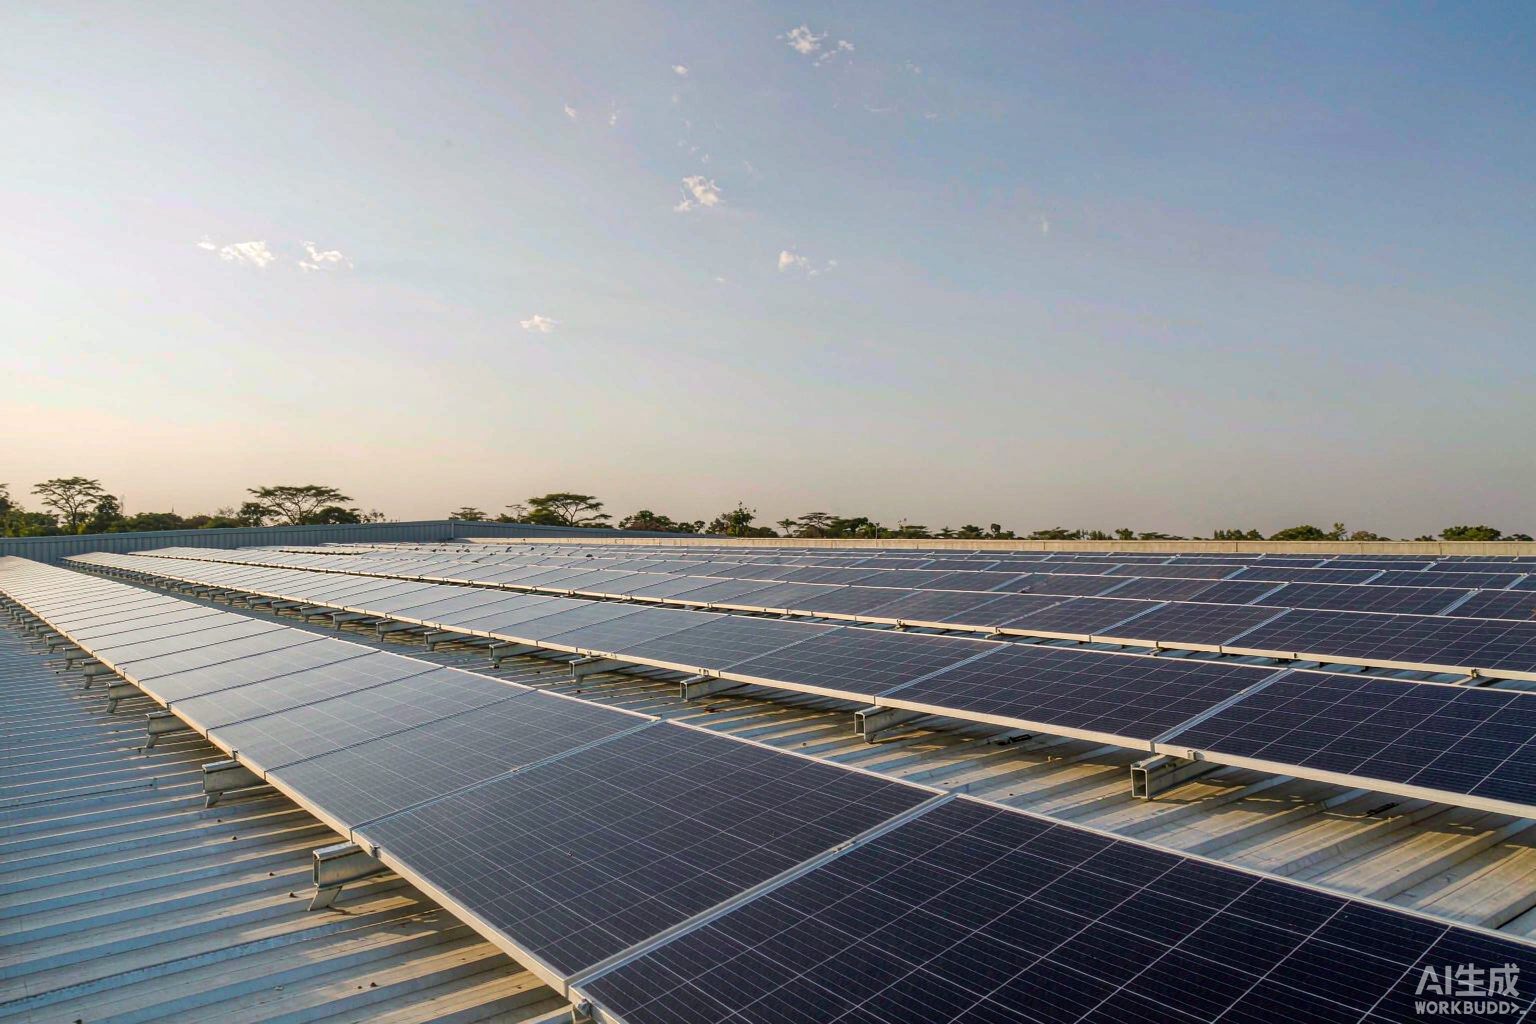
على مدى الأسابيع القليلة الماضية، شهدت أسعار العديد من المواد الأولية الأساسية لأنظمة الطاقة الشمسية الكهروضوئية ارتفاعاً متسارعاً.
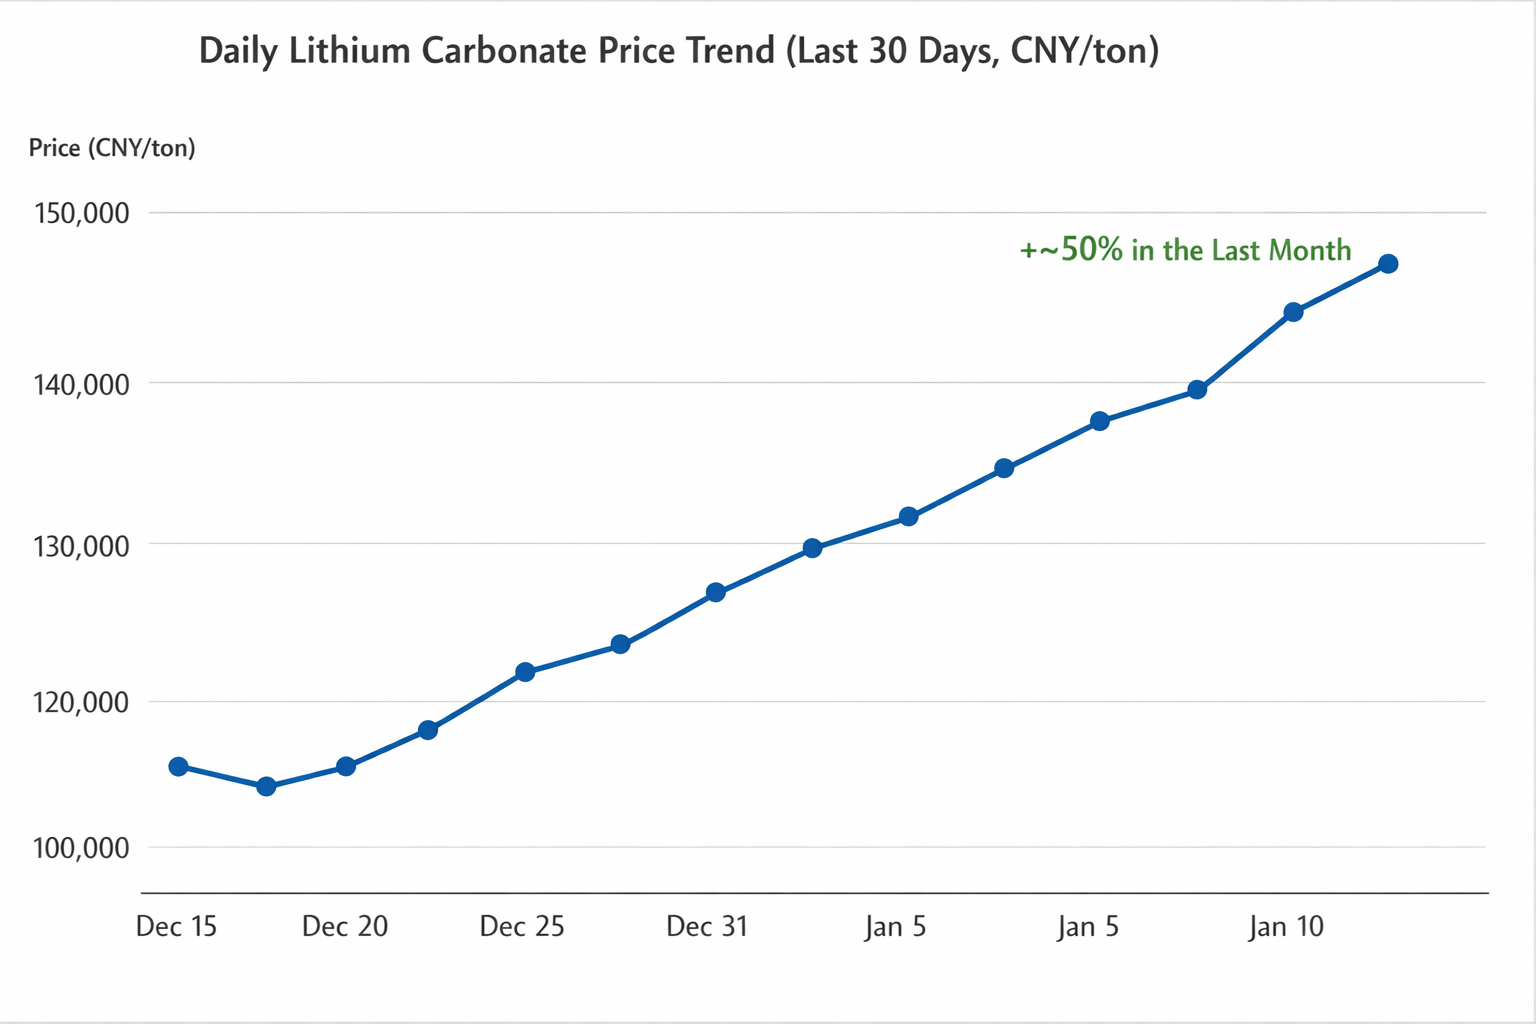
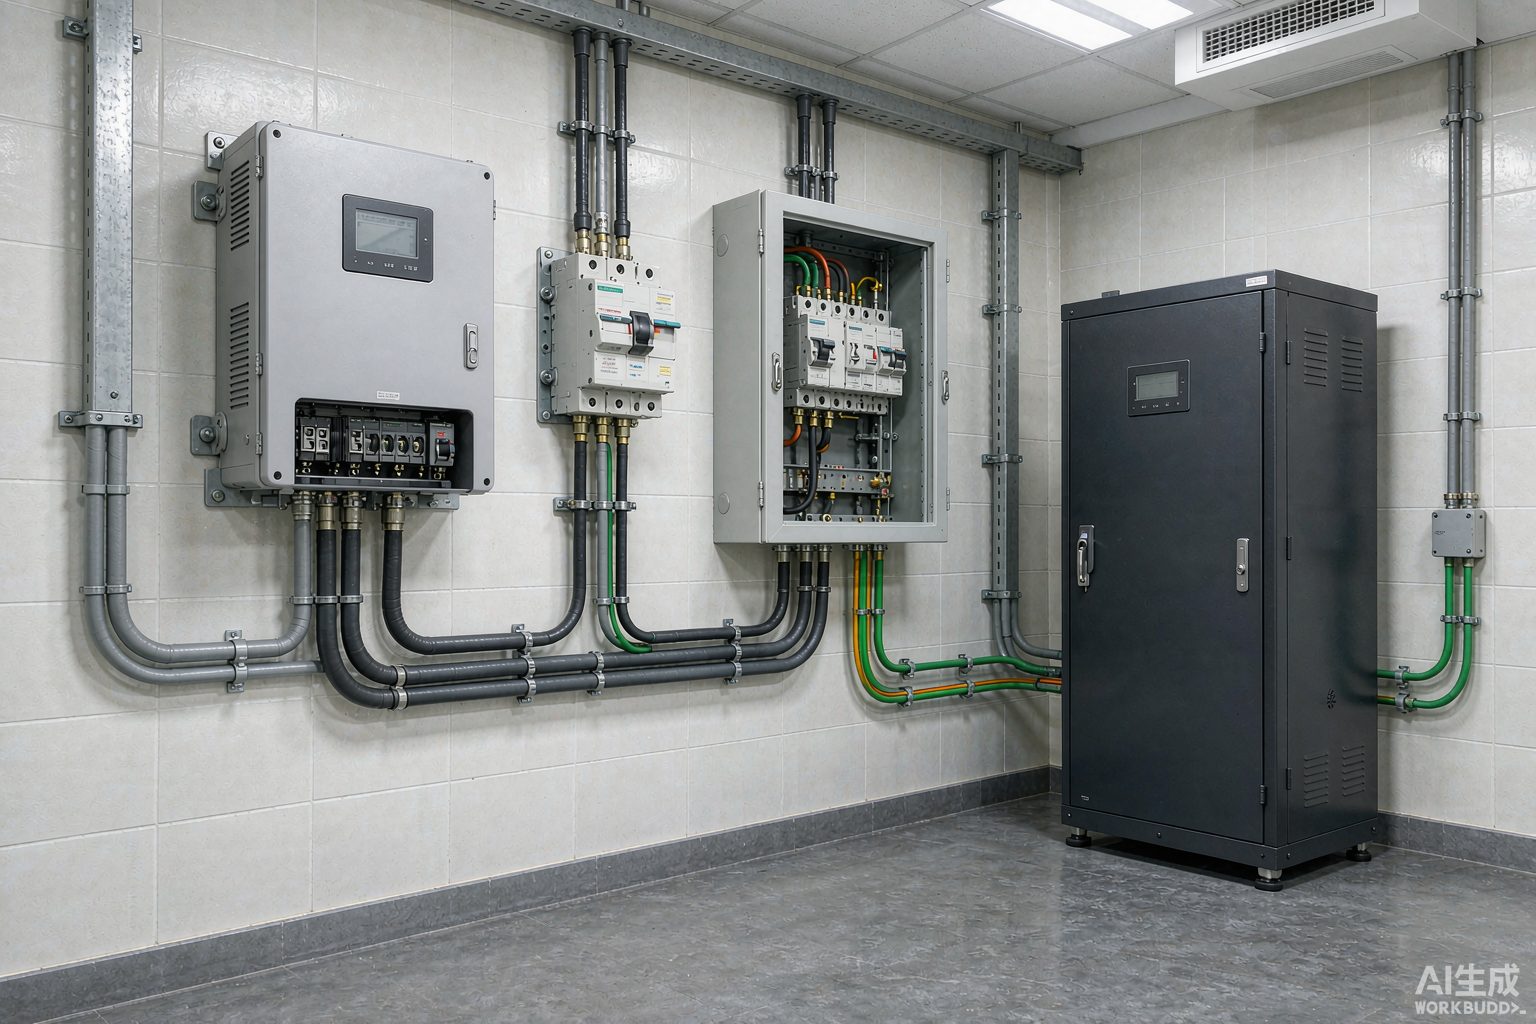
شهدت أسعار كربونات الليثيوم انتعاشاً قوياً نتيجة لانخفاض المخزونات، وتوقعات الطلب المدفوعة بالسياسات، والنمو المستمر في الطلب على البطاريات من قطاعي تخزين الطاقة والمركبات الكهربائية. وهذا بدوره يزيد من تكاليف أنظمة الطاقة الشمسية الكهروضوئية المزودة بأنظمة تخزين الطاقة.
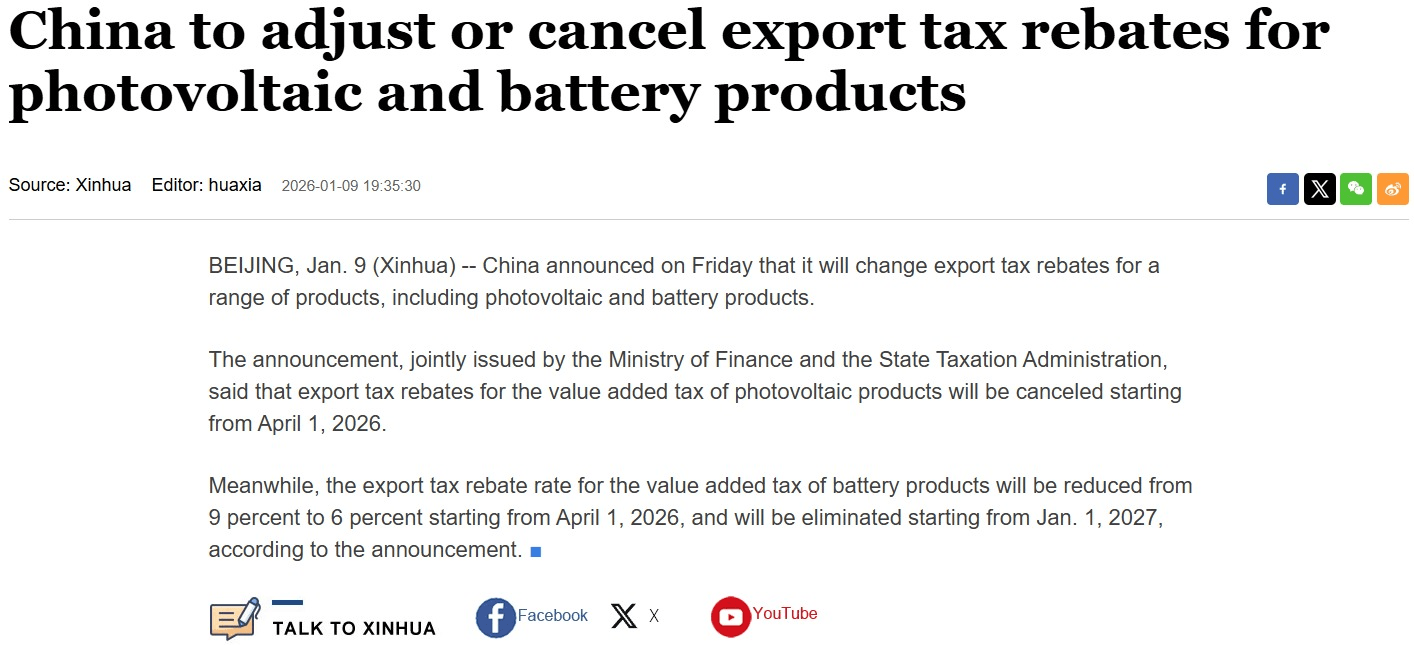
ستقوم الصين بإلغاء خصومات ضريبة القيمة المضافة على صادرات منتجات الطاقة الشمسية الكهروضوئية ابتداءً من شهر أبريل، مع التخلص التدريجي من خصومات بطاريات الليثيوم.
يمثل هذا زيادة هيكلية في تكلفة تصدير منتجات الطاقة الشمسية الكهروضوئية وتخزين الطاقة، مما يدفع المصنعين إلى رفع الأسعار وتسريع الشحنات قبل التنفيذ.
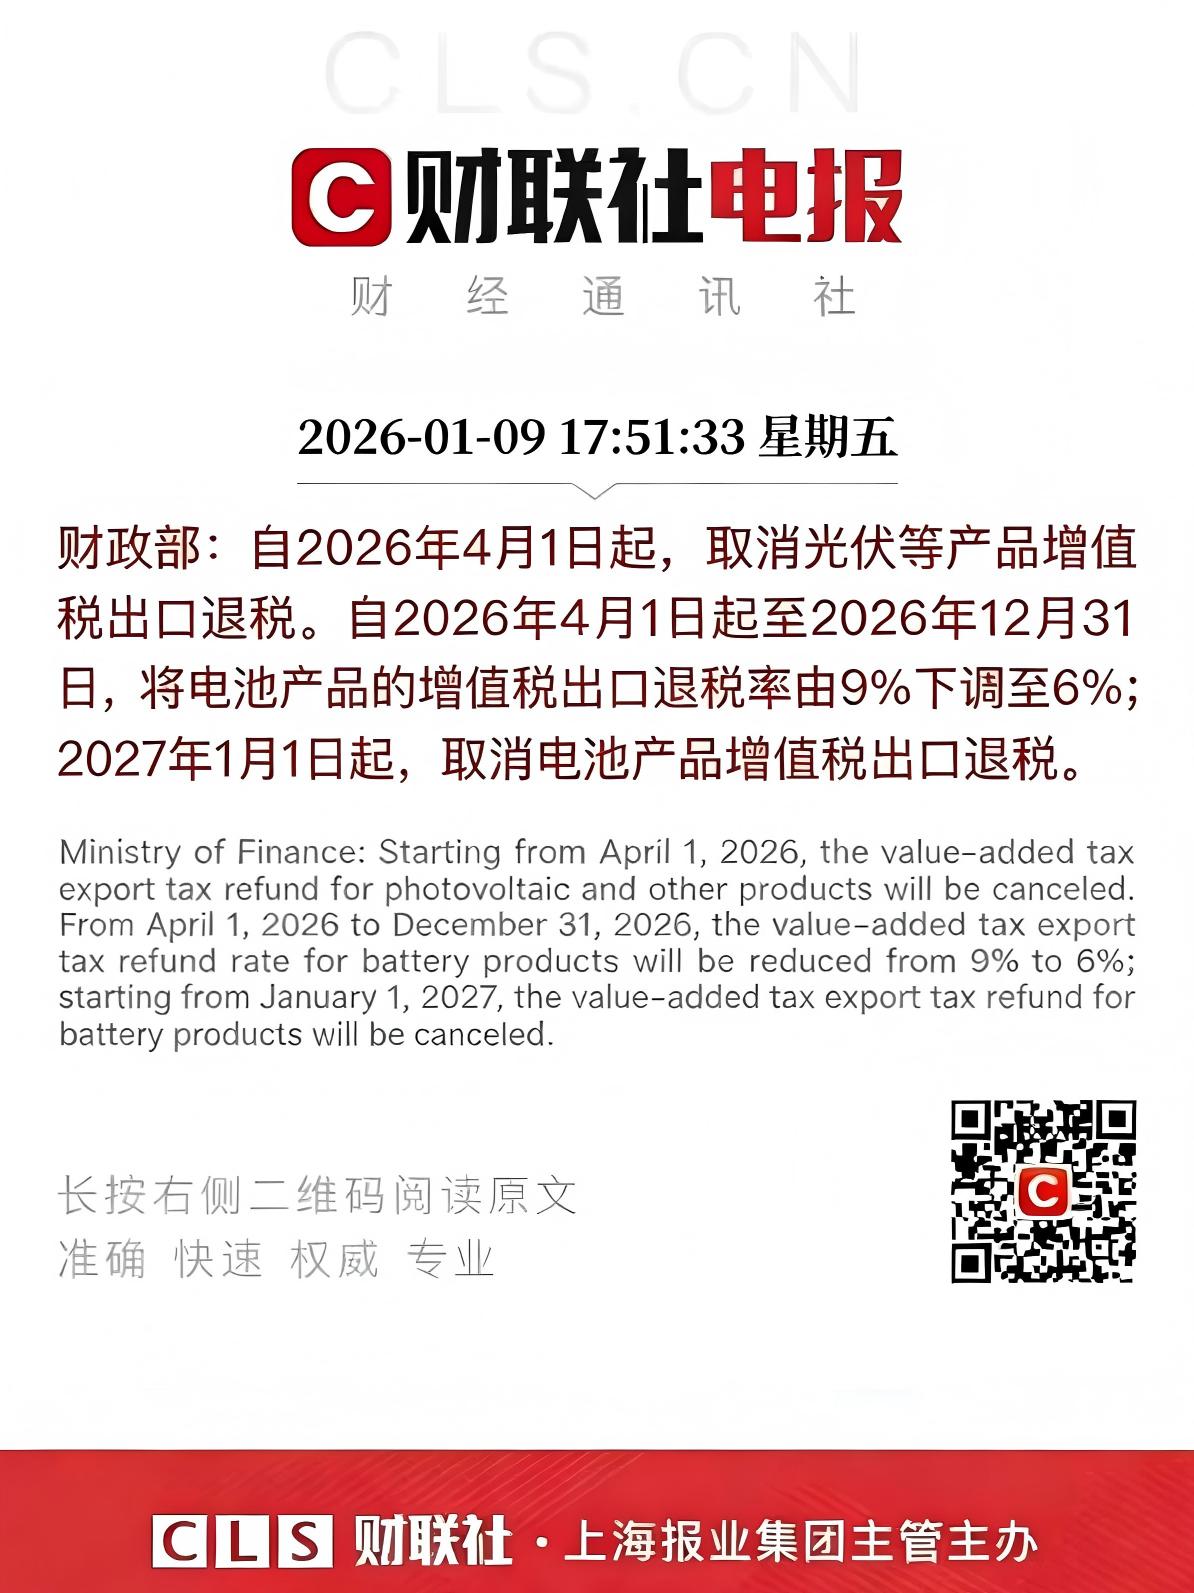
إن تقارب التضخم في أسعار المواد الخام والتغيرات في السياسات يؤدي إلى تضييق نطاق فرص الشراء.
*يحمل تأخير الشراء الآن مخاطر تكلفة أعلى.
*تساعد الطلبات المبكرة في تثبيت الأسعار وتأمين الإمدادات.
Three things follow from the cost moves above. First, panel prices stop falling and start tracking upstream polysilicon and aluminium. Second, storage gets more expensive before it gets cheaper, because lithium carbonate leads the battery chain. Third, the window to lock a price narrows: the convergence of raw material inflation and the export rebate change means quotes that were valid for thirty days are now valid for ten.
For procurement teams the practical response is to fix the specification early and price the whole bill of materials at once, rather than optimising panels first and discovering the battery cost later. A solar industry buyer who locks cells, cells-to-module conversion and balance of system in one contract avoids the worst of the gap between a panel quote and a delivered system price.
It also changes where the savings are. When module prices rise, the engineering margin moves to configuration: right-sizing the array to the real load, cutting oversized inverter capacity, and specifying storage against the overnight load rather than a rule of thumb. That is work that shows up in the bill of materials, not in the headline price per watt.
Procurement teams tracking these moves can cross-check the policy side against the US DOE Solar Energy Technologies Office, which publishes solar industry cost and deployment data on the same cycle. For the import and duty side of a purchase, see our Philippines solar import guide.
If you are budgeting a build this year, the honest answer is that the solar industry has moved from a deflationary market to a volatile one. Plan for a price band rather than a single number, and ask your supplier which components in the quote are fixed and which track the spot market.
We publish our own solar industry bill-of-materials pricing with a validity window and a named component list, so a buyer can see exactly which line items moved and why when a quote is refreshed. That transparency is the only workable answer to a market where the same system prices differently three weeks apart.
One more practical note for anyone pricing this year: the solar industry gap between a panel quote and a delivered system price is where most budgets break, because freight, duties and balance of system move on different cycles from the modules themselves. Ask for all three in one number.
 English English
 Arabic
 Spanish
 French
 Dutch
 Portuguese