Taal
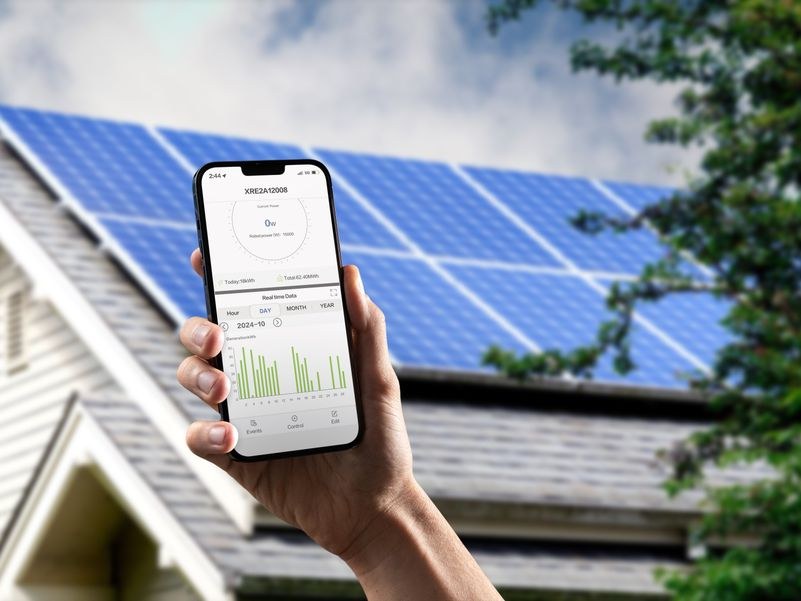
An independent power producer is a private company that owns, develops and operates electricity generation assets and sells the power to a utility, grid operator or corporate offtaker under a long-term contract. Unlike a regulated utility, an independent power producer does not own the transmission and distribution network - it generates electricity and sells it wholesale, usually through a power purchase agreement (PPA) that fixes the tariff for 10-25 years.
In solar energy, independent power producers are the companies behind utility-scale solar farms, commercial rooftop portfolios and hybrid solar-plus-storage plants. They take on the development risk - land, permits, grid connection, financing - and are paid per kilowatt-hour delivered, which makes the solar independent power producer model one of the most bankable structures in renewable energy today.
For B2B buyers in Nigeria, Kenya, Ghana and the Philippines, understanding how independent power producers work is practical: it explains who your real competitors are, how a solar PPA is priced, and whether you should build, buy or contract your own generation. This guide covers that whole chain.
An independent power producer differs from a solar EPC contractor in one fundamental way: the independent power producer keeps ownership of the asset and sells energy, while an EPC contractor builds the plant and hands it over. That shifts the revenue model from a one-off construction margin to recurring energy revenue.
The typical independent power producer revenue stack has four layers:
Because revenue is contract-backed, independent power producers are financed on debt-heavy structures, typically 70-80% project finance with 20-30% equity. Lenders underwrite the offtaker credit, the resource assessment and the equipment warranty - which is why these developers are rigorous about module and inverter quality, and why an IPP is one of the most demanding solar customers in any market.
Buyers often compare four structures when they need large-scale solar power. The table below shows how an independent power producer fits alongside them.
Model | Who owns the plant | Buyer pays | Het meest geschikt voor |
Independent power producer (IPP) | The IPP | Per kWh under a PPA | Buyers who want zero capex and long-term tariff certainty |
EPC turnkey purchase | The buyer | One-off project price | Buyers with capital who want to own the asset and the savings |
Lease / rent-to-own | Lessor, then buyer | Fixed monthly payment | Buyers who need capex relief but want eventual ownership |
Captive / self-generation | The buyer | Capex plus O&M | Factories and mines with high self-consumption |
The decisive variable is the offtaker's credit strength. An IPP selling to a state utility takes on payment-risk that is priced into the tariff; one selling directly to a creditworthy factory or hotel group can offer a materially lower tariff because the counterparty risk is lower. Many African and Southeast Asian developers now target commercial and industrial offtakers specifically for this reason - see our guide to solar PPA structures in Kenya for a market example.
Three forces are accelerating the shift toward IPP structures in Africa, Southeast Asia and the Caribbean.
Industrial electricity tariffs in Nigeria and Kenya have repeatedly climbed, while the levelised cost of solar-plus-storage keeps falling. That spread is the entire IPP opportunity - a developer can contract power below the grid tariff and still earn a return. Our analysis of diesel versus solar cost in Nigeria shows a similar spread against backup generators.
Multinational manufacturers, hotel groups and banks increasingly must report Scope 2 emissions. An independent power producer PPA delivers renewable energy attribute certificates without the buyer carrying the construction risk, which turns a sustainability target into a procurement formality.
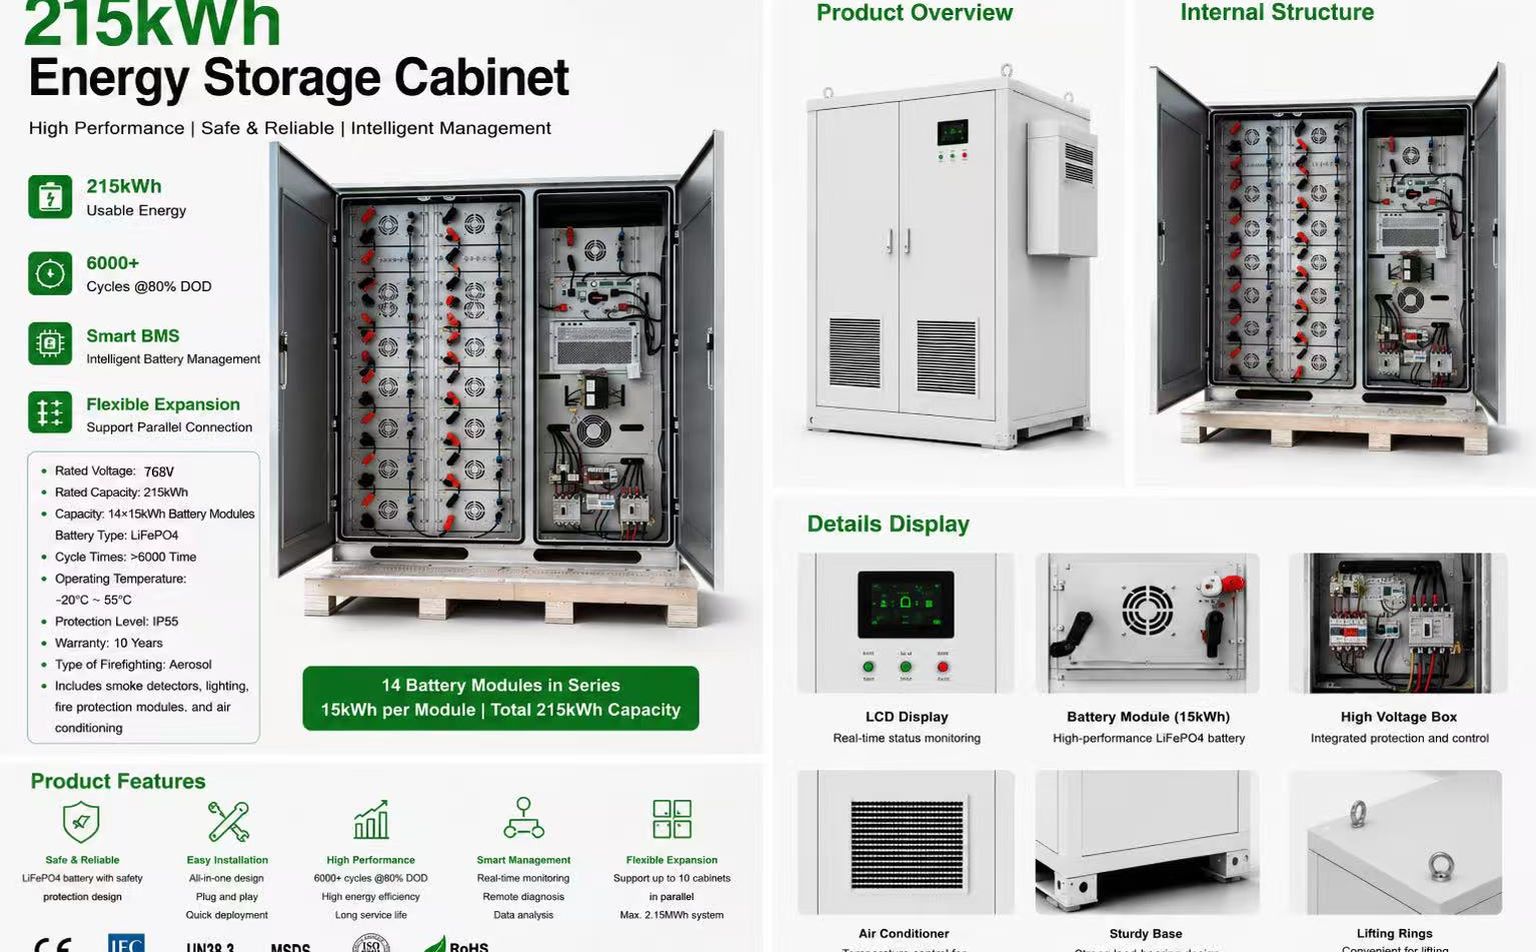
Historically an IPP could only sell energy when the sun shines. With utility-scale battery storage - like the systems described in our BESS in Nigeria import guide - solar developers can now sell firm capacity into evening peaks and ancillary markets, improving project returns substantially.
Every utility-scale IPP project follows the same sequence, whether it is a 5 MW plant in Ghana or a 100 MW portfolio in the Philippines.
Because project finance lenders underwrite the equipment, an IPP applies stricter procurement criteria than a typical self-generation buyer.
For suppliers, this is why winning independent power producer business is an engineering and documentation exercise rather than a pricing contest. A solar supplier that cannot produce bankable paperwork is invisible to an independent power producer regardless of price.
These developers exist to hold risk that utilities and corporate buyers do not want. The main exposures are:
These risks are why developers run long technical due-diligence processes, and why the equipment supply chain matters as much as the PPA economics. For independent market data on PPA pricing and project costs, see the IRENA renewable power generation cost reports, which track global solar and storage benchmark tariffs.
Mars Solar supplies solar modules, hybrid inverters and lithium battery storage to IPPs, EPC contractors and commercial offtakers across Africa, Southeast Asia, the Caribbean and the Middle East. For IPP projects we support the procurement stage with bankable documentation, factory audit access and container-level logistics planning.
If you are structuring an IPP project and need a supply partner who understands lender requirements, contact our engineering team for a project-specific configuration and landed-cost estimate. For broader context on import routes and duties, our solar import Nigeria guide En Philippines solar import guide cover the procurement side end to end.
The independent power producer has become the central vehicle for scaling solar generation in markets where utilities cannot fund capacity fast enough. For buyers, an IPP PPA converts a large capital project into an operating expense with a fixed tariff. For suppliers, these developers are the most demanding - and most valuable - customer segment, because they buy on bankability, certification and supply reliability rather than price alone.
As battery storage continues to fall in cost and grid tariffs continue to rise, the IPP model will keep expanding from utility-scale plants into commercial and industrial portfolios. Understanding how these developers structure, finance and procure solar projects is now essential knowledge for anyone selling solar equipment into emerging markets.
 English English
 Arabic
 Spanish
 French
 Dutch
 Portuguese